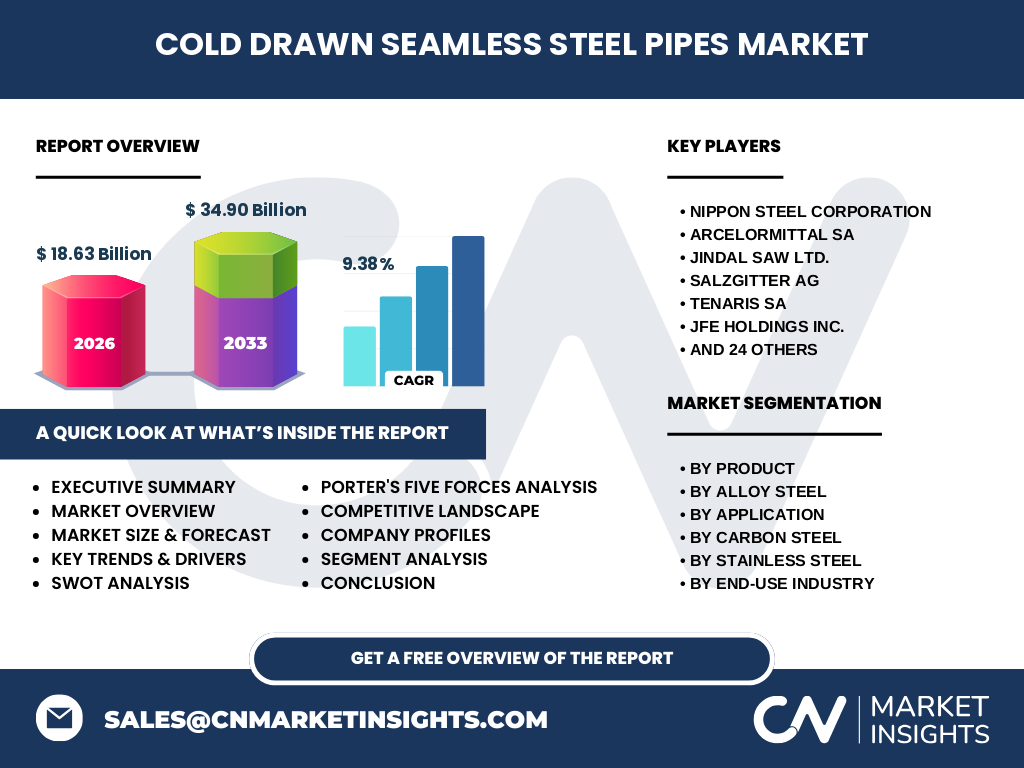
Market overview of the Cold Drawn Seamless Steel Pipes Market
Our analysis indicates that the Cold Drawn Seamless Steel Pipes Market is valued at 18.63 Billion in 2026, serving critical infrastructure sectors. This industry encompasses high-precision tubular components manufactured via cold drawing over a mandrel, ensuring stringent dimensional tolerances and superior surface finishes mandated by ASTM and API standards.
Key market drivers, restraints, challenges, and opportunities shaping the Cold Drawn Seamless Steel Pipes Market
Growth is propelled by rising demand for high-pressure fluid transfer lines and strict ISO regulatory compliance in heavy machinery. However, market restraints involve volatile raw material costs for primary iron ore and nickel, while opportunities lie in expanding precision instrumentation applications across rapidly industrializing economies.
Emerging trends and growth patterns in the Cold Drawn Seamless Steel Pipes Market
The shift toward advanced metallurgical formulations highlights current industry trends, particularly increased adoption of high-alloy and austenitic stainless steel grades. Producers are leveraging continuous mandrel rolling technology to improve grain structure uniformity and reduce post-processing machining overhead for end users.
COVID-19 impact analysis and recovery trajectory
Pandemic-induced supply chain bottlenecks severely disrupted raw material flows and port logistics globally. Recovery has been robust, driven by stimulus-backed infrastructure investments and a rebound in automotive applications that accelerated demand for reliable boiler and heat exchanger tubes.
Competitive benchmarking and strategic market concentration
The market features intense competition among global giants like Nippon Steel Corporation, ArcelorMittal SA, and Tenaris SA, alongside specialized players like Jindal Saw Ltd. and Salzgitter AG. Market leaders maintain an edge through backward integration into raw steel production and proprietary cross-roll piercing capabilities.
Executive summary of the Cold Drawn Seamless Steel Pipes Market
Our comprehensive research confirms a dynamic trajectory, projecting the market to expand from 18.63 Billion in 2026 to 34.90 Billion by 2033 at a CAGR of 9.38%. Strategic investments in multi-stand plug mill technologies are essential for capturing high-margin opportunities in power generation and oil and gas sectors.
Market forecast from 2027 to 2033
Based on our econometric models, the market is set to achieve a robust 9.38% CAGR, scaling from 2026 levels to reach 34.90 Billion by 2033. This expansion is underpinned by sustained capital expenditure in global energy infrastructure and rigorous mandates for leak-proof fluid transfer systems.
Segmentation analysis across product, alloy, application, and production process
Segmentation spans multiple dimensions:
- Product: Carbon Steel, Alloy Steel, Stainless Steel
- Alloy Steel: Low and High Alloy Steel
- Application: Precision Instrumentation, Boiler Tubes, Heat Exchanger Tubes, Hydraulic Applications, Fluid Transfer Lines, Rifled Tubes, Bearing Pipes, Mining, Automotive, and General Engineering
- Production Process: Cross-Roll Piercing, Multi-Stand Plug Mill, and Continuous Mandrel Rolling
Regional market analysis and geographic performance
Geographic performance exhibits distinct regional characteristics, with Asia-Pacific dominating consumption due to expansive infrastructure and construction projects. Meanwhile, North America and Europe focus heavily on advanced automotive and precision instrumentation applications, driven by strict environmental compliance enforced by agencies like the EPA.
In-depth regional review of manufacturing hubs and logistics
Key manufacturing hubs in East Asia and Western Europe leverage proximity to major maritime ports to streamline export logistics. Regional constraints involve navigating trade tariffs on steel imports and adhering to localized Pressure Equipment Directive (PED) standards that dictate rigorous hydrostatic testing for all seamless pipes.
Company profiles and strategic positioning of leading participants
Industry leaders such as JFE Holdings Inc., Tata Steel Limited, and US Steel Tubular Products Inc. focus on high-value alloy and stainless steel segments. Specialized domestic firms like Salem Tube International Limited and HandyTube Corporation carve out niches by supplying ultra-precise instrumentation and hydraulic tubing.
Porter's Five Forces analysis of the industry
The industry experiences moderate-to-high supplier power due to concentrated iron ore markets, while buyer power is tempered by the specialized technical requirements of seamless pipes. Threat of substitution remains low in high-pressure applications, though intense rivalry among established global mills keeps profit margins tightly bound to operational efficiency.
SWOT analysis of the Cold Drawn Seamless Steel Pipes Market
Strengths: Exceptional tensile strength and dimensional accuracy. Weaknesses: High capital expenditure for cold drawing infrastructure. Opportunities: Growth in renewable energy infrastructure and electric vehicle thermal management. Threats: Raw material price volatility and substitution threats from advanced composite materials in low-pressure niches.
Value chain analysis from raw materials to end-users
The value chain initiates with iron ore and scrap metal sourcing, transitioning through electric arc furnaces and continuous casting into primary billets. Billets undergo hot extrusion followed by specialized cold drawing over mandrels, culminating in rigorous non-destructive testing before distribution to end-users in oil and gas and power generation.
Investment insights and high-potential areas
Strategic analysis highlights high-potential investment in facilities capable of producing austenitic and martensitic stainless steel pipes for aggressive corrosive environments. Investors should prioritize mills integrating automated multi-stand plug mill lines to drastically reduce operational downtime and scale production capacity efficiently.
Conclusion and key takeaways for stakeholders
The data clearly demonstrates that capturing growth in this 34.90 Billion market by 2033 requires aligning product portfolios with high-margin sectors like precision instrumentation and advanced automotive engineering. Companies emphasizing technological modernization will outperform competitors relying on legacy manufacturing frameworks.
Research methodology and data triangulation
Baseline estimates are meticulously triangulated by combining official trade registry data from customs authorities, primary stakeholder interviews with C-suite executives across major pipe mills, and secondary macroeconomic indicators tracking global industrial manufacturing output and energy sector capital expenditures.
Scope of the report and coverage parameters
This report covers global market sizing, historical evaluations, and forecasts through 2033, analyzing market dynamics across specified product lines, production processes, and end-use industries. Limitations include inherent forecasting uncertainties tied to unforeseen geopolitical trade shifts and sudden macroeconomic commodity price fluctuations.
Recent developments, partnerships, and strategic moves
Recent industry momentum features strategic acquisitions, capacity expansions, and joint ventures aimed at securing localized supply chains. Key players are investing in digital twinning for their cold drawing lines to optimize energy consumption and meet stringent corporate sustainability metrics demanded by global industrial clients.